Commercial insurance built around what you actually do.
A contractor, a restaurant and an online business do not create the same risks. Start with your operation, then build the coverage around it.
What kind of business do you run?
Your industry changes the exposures, questions and coverage that should be reviewed.
ContractorTools, job sites, liability, vehicles
RestaurantPremises, property, liability, equipment
RetailStock, premises, liability, interruption
ProfessionalOffice risks, liability, professional exposures
E-CommerceProducts, inventory, liability, cyber considerations
CleaningLiability, equipment, customer premises
TechnologyProfessional, cyber and property exposures
OtherTell me what your business does
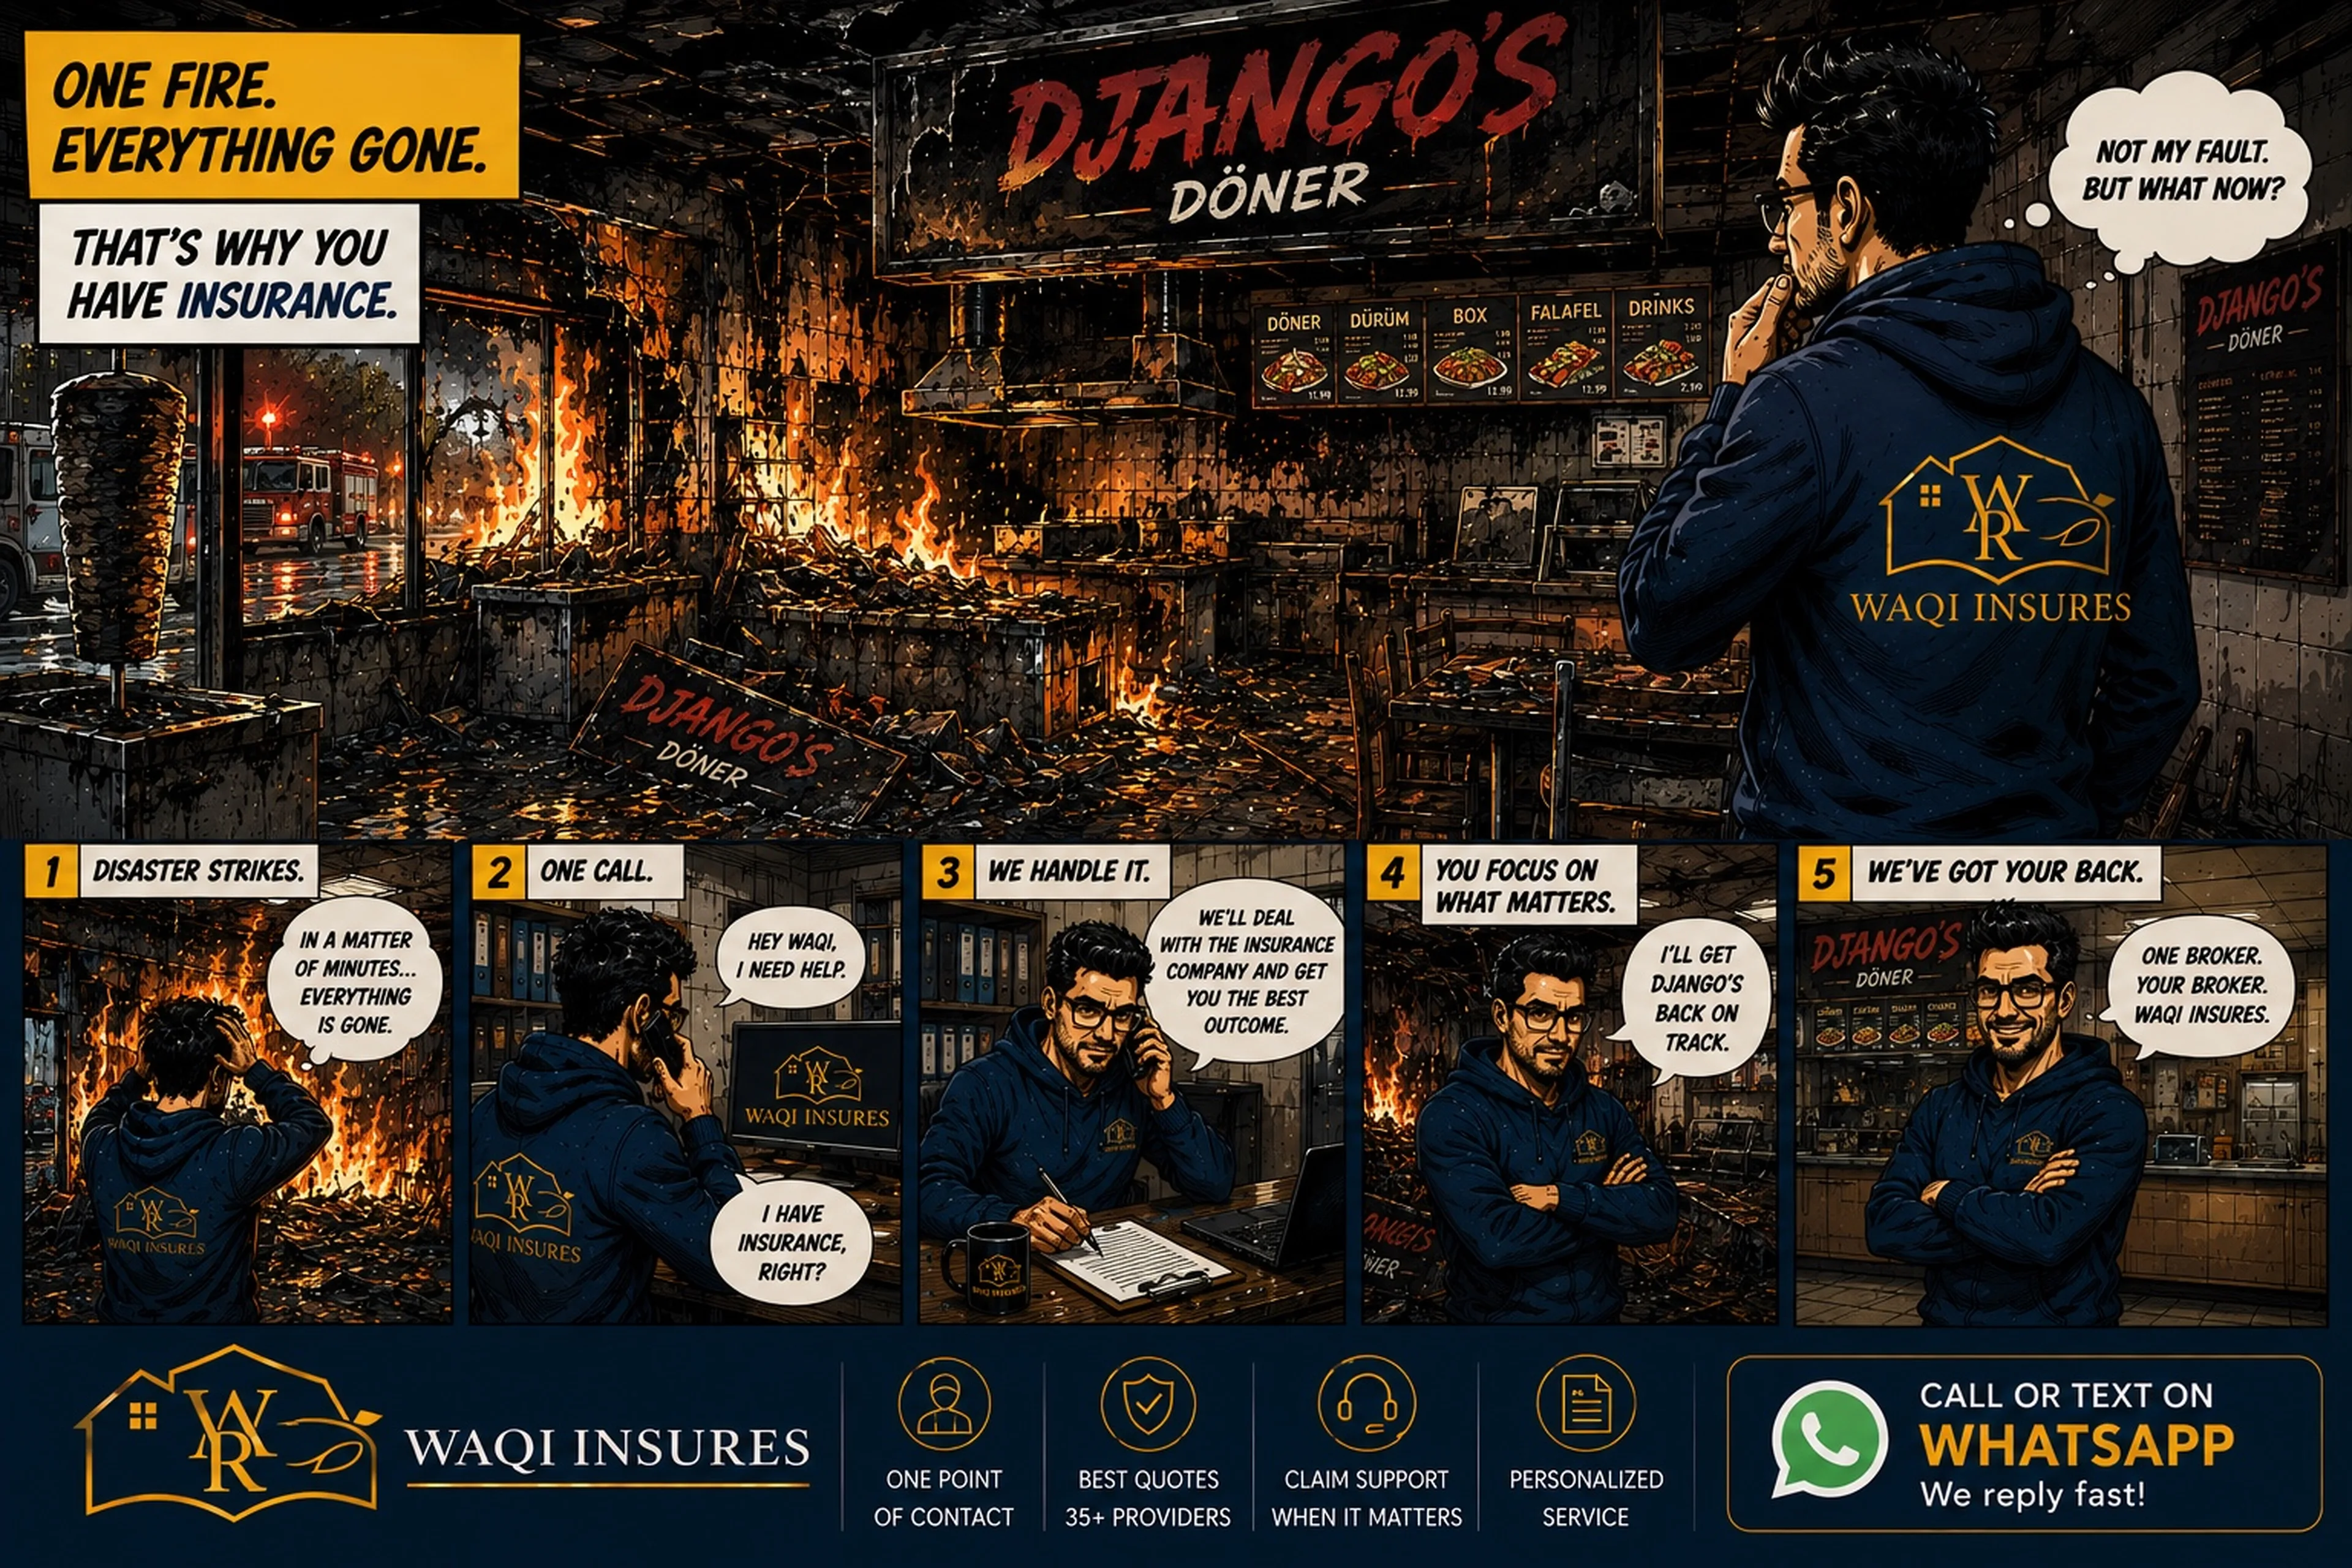
COMMERCIAL FIRE
Some scenarios are better left in the comics.
We hope you never need your insurance — but if you do, we’ll be ready.
Common commercial coverages.
The right combination depends on your operation, contracts, property, vehicles and the work you perform.
Commercial General Liability
Protection for certain third-party bodily injury and property damage claims arising from business operations.
Property & Equipment
Coverage can be structured around premises, stock, tools, equipment and other insured business property.
Commercial Auto
Vehicles used for business may require coverage designed around the actual commercial use.
Example: contractor coverage.
A contractor may need more than one policy section. Common considerations can include liability, tools and equipment, commercial auto and property protection.
Start with the work
The type of work, annual revenue, employees, subcontractors, job locations and contracts can all change what an insurer needs to know.
Tell me what your business does.
We can start from the actual operation instead of forcing it into a generic template.